
Metals MIning, Trade
Cobalt & Manganese: 2025-2026 Rally, The Tap and The Valve
Oct
The Tap and the Valve
The DRC controls roughly three-quarters of the world’s cobalt. In 2025 it discovered that controlling the mine matters far less than controlling the exit — and Gabon has just announced it plans to do the same thing with manganese.
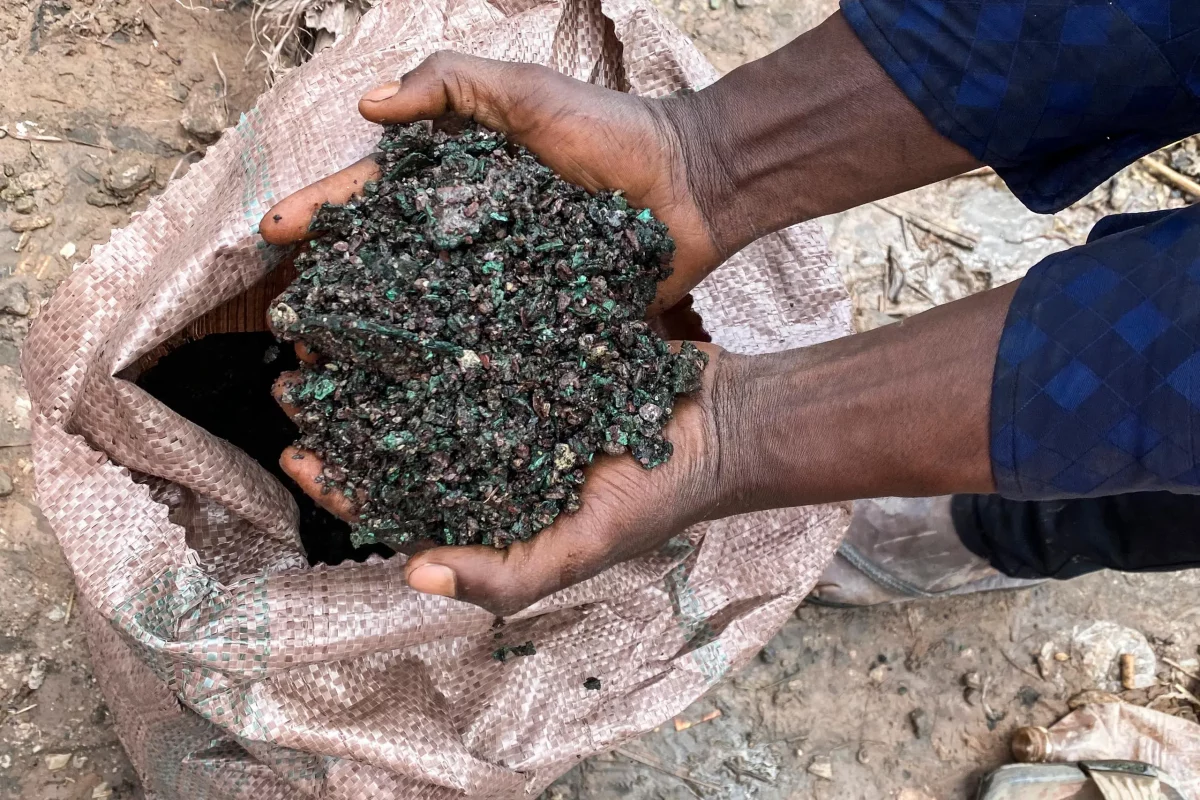
Most commodity price shocks come from a mine going offline, a war, or a demand surge nobody priced in. Cobalt’s 2025-2026 rally came from something rarer: a government deciding, deliberately and on paper, exactly how much of its own resource the rest of the world would be allowed to have. The Democratic Republic of Congo, source of roughly three-quarters of the world’s mined cobalt, banned exports outright in February 2025, replaced the ban with a hard quota that October, and watched prices more than double within the year. It is one of the cleanest demonstrations in recent commodity history of what happens when a producing state stops taking the price the market offers and starts setting the volume it allows out the door.
01 — How the Squeeze HappenedFrom Nine-Year Low to Quota Regime in Twelve Months
Cobalt entered 2025 near a nine-year price low, the tail end of a glut driven by surging Indonesian nickel-byproduct supply and record Congolese output — production had reached roughly 204,000–211,000 tonnes in 2024, more than double the country’s output just a few years earlier. Cobalt hydroxide delivered to China had fallen to around $5.60 per pound, near or below production cost for many operations. On 22 February 2025, the DRC’s Authority for the Regulation and Control of Strategic Mineral Substances’ Markets — ARECOMS — suspended cobalt exports outright, intending it as a temporary “reset.” The suspension ran far longer than initially signalled, and on 16 October 2025 it was replaced with a formal quota system: a hard annual export ceiling of 96,600 tonnes for both 2026 and 2027, of which 87,000 tonnes is distributed to producers on a pro-rata basis tied to historical exports, with the remaining 9,600 tonnes held under ARECOMS’s own discretionary control as a strategic reserve.
| Milestone | Date | Detail |
|---|---|---|
| Export ban imposed | 22 Feb 2025 | Prices near $21,000/t; intended as a market “reset” |
| Quota system replaces ban | 16 Oct 2025 | 96,600t annual cap set for 2026 and 2027 |
| Entering 2026 | 1 Jan 2026 | Cobalt metal at $56,414/t — more than double the Feb 2025 low |
| Q2 quota forfeiture deadline | 30 Jun 2026 | Unshipped H1 allocations automatically revoked, transferred to state reserve |
| Customs platform failure | 1–13 Jul 2026 | ARECOMS failed to notify customs to keep processing quota-linked exports; producers appealed to the PM |
2025 has demonstrated the risks associated with having a single country being responsible for the majority of supply.Roman Aubry, Nickel & Cobalt Analyst, Benchmark Mineral Intelligence
02 — Who Actually Holds the QuotaThree Companies, Sixty Percent of the Allocation
The quota’s practical effect falls unevenly. CMOC Group, Glencore and Eurasian Resources Group together control over 60% of total permitted export allocations across five primary mining operations, with CMOC alone — fresh off a 2025 production record of 117,549 tonnes — allocated roughly 31,200 tonnes for 2026 against production guidance of 100,000–120,000 tonnes. The gap between what these companies can mine and what they are permitted to export is, by design, the entire point: the DRC produced an estimated 100,015 tonnes of cobalt in 2025 but exported only 44,333 tonnes, meaning more than half of national output sat inside the country rather than reaching global markets. Fastmarkets projects a 10,700-tonne global deficit for 2026 against demand of roughly 292,300 tonnes; other forecasters, working from export-adjusted rather than total-production balances, put the effective shortfall considerably higher.
Under the old ban-or-no-ban model, the question facing buyers was binary: exports permitted or not. The quota model replaces that with something harder to price: quarterly compliance windows, forfeiture deadlines, and a regulator that has already demonstrated both the will and the administrative capacity to disrupt its own system, as the July 2026 customs platform failure showed. Cobalt-exposed counterparties now need to track ARECOMS’s operational cadence as closely as the headline tonnage figures.
03 — The Manganese ParallelGabon Is About to Try the Same Playbook
Cobalt is not the only Africa-dominated battery-adjacent mineral where a producing government has decided raw export is a bad trade. Manganese — used in steelmaking at roughly 85%+ of global consumption, and increasingly in EV battery cathodes via LMFP and NMC chemistries — is overwhelmingly African-sourced: South Africa alone produces around 7.2–7.4 million tonnes a year (roughly 35–37% of global supply, hosted mainly in the Kalahari Manganese Field), with Gabon a close second via Eramet’s Comilog-operated Moanda mine and Ghana a smaller but growing fourth-largest global producer.
| Country | 2025 Manganese Output (approx.) | Beneficiation Move |
|---|---|---|
| South Africa | ~7.2–7.4Mt/yr | Manganese Metal Company commissioning South Africa’s first battery-grade HPMSM plant, 2026; Giyani Metals demonstration facility targeting feasibility completion Q2 2026 |
| Gabon | ~7Mt/yr (Moanda mine, Eramet/Comilog) | Government-announced ban on raw manganese exports from January 2029; July 2026 MoU with Eramet to process up to 700,000t/yr domestically by 2031 |
| Ghana | ~820,000t+/yr, rising (Nsuta mine) | Planned refinery adjacent to Nsuta mine to produce battery-grade manganese, developed with Chinese partner TMI |
Gabon’s planned 2029 export ban is, structurally, the same move the DRC has already made with cobalt: convert control of the raw resource into control of where the value-added processing step happens, rather than letting concentrate leave the country for refining elsewhere. China currently controls over 85% of global refining capacity for high-purity manganese sulphate monohydrate (HPMSM), the battery-grade product buyers actually need — which is precisely the chokepoint Gabon’s 2029 policy, and South Africa’s parallel HPMSM investments, are aimed at breaking.
04 — OutlookWhat We Are Watching Into Year-End
- Quota ComplianceActual 2026 export volumes against the 96,600t ceiling, and whether further forfeiture-and-reallocation episodes recur, will determine how much of the current price premium is durable.
- ARECOMS DiscretionWhether the regulator releases, withholds, or reduces its 9,600t strategic reserve in response to price moves is now a standing source of market volatility.
- Gabon’s CountdownThe 2029 manganese export ban gives producers and buyers roughly three years to build domestic processing capacity or find alternative supply — a shorter runway than it may appear.
- Indonesia’s CeilingIndonesian nickel-byproduct cobalt supply is the main swing factor that could ease DRC-driven tightness, but has so far proven insufficient to replace lost Congolese volumes.
Fava Herb Metals & Mining Intelligence Report: Cobalt
Institutional-grade market intelligence on Africa’s metals and mining sector — global price forecasts, country-level production data, and East African trade and refining analysis, from Fava Herb’s Commodities Desk. A licensed, sourced data product for traders, investors, and trade financiers.
Book: Returning To Nature’s Ancient Pharmacy -An African Approach To Natural Remedies
What You’ll Discover:
- Daily Herbal Remedies backed by Scripture and tradition
- Natural healing foods like raw honey, fermented drinks, and superfruits
- Uses of animal fats like tallow, ghee, and bone broth
- African healing plants like hibiscus, tamarind, and baobab
- Teas and Adaptogens for stress, energy, and hormone balance
- Spiritual insights on God’s design for healing and wellness
- Practical recipes, homemade remedies, and devotional reflection

